Analysis: India’s power-sector emissions flat for two years due to clean-energy surge
A surge in clean energy has kept carbon dioxide (CO2) emissions in check across India’s power sector, with no growth from the first half of 2024 to the same period in 2026.
This guest post is by:
Lauri Myllyvirta, lead analyst at Centre for Research on Energy and Clean Air (CREA)
Anubha Aggarwal, India analyst at CREA
This is the first time in more than 50 years that there has been no growth in India’s coal power over a two-year period, even as electricity demand grew overall.
At the same time, both oil and gas consumption have fallen across the nation for two years in a row, helping alleviate the shock of the Hormuz crisis.
Nevertheless, the new six-monthly analysis for Carbon Brief shows that India’s emissions grew by 3.7% year-on-year in the first half of 2026, due to increases from steel, cement and other sectors.
Other key findings for the first half of 2026 include:
- India’s power-sector emissions flatlined at 2024 levels, after a 2.2% decline in the first half of 2025 and a 2.3% rise in the same period this year.
- Clean energy met all of the 7% rise in India’s electricity demand over the two years, adding 63 terawatt hours (TWh), equivalent to the total demand of Switzerland.
- India has added 77 gigawatts (GW) of solar in this two-year period, helping meet 60% of the rise in electricity demand overall.
- While fossil-fuel generation stagnated, generators added 8.5GW of new coal capacity, leading to fewer running hours and increased costs to electricity consumers.
- CO2 emissions from oil and gas fell by 7% year-on-year, extending a reduction that began in 2025, despite higher demand for road transport fuels.
- Steel and cement emissions grew by 8% year-on-year, reaching a 23% share of India’s total CO2 in the first half of 2026.
If the pace of India’s clean-energy expansion is to continue, it will need to upgrade its electricity grid, rapidly build out energy storage and boost the flexibility of coal power.
While clean-energy expansion is covering most or all of India’s power-demand growth, the fossil-fuel industry continues to pursue major capital investments.
This includes large amounts of new coal-power capacity, ambitious plans for the conversion of coal-to-chemicals and efforts to boost domestic coking coal production for the steel sector.
While CO2 output from the power sector is flat, with oil and gas in decline, India’s emissions still went up due to the contribution from industry.
India lags behind its competitors – including most large emerging economies – when it comes to electrifying its industrial sector.
Faster progress would enable clean electricity to substitute for fossil fuels in industry, as well as for power, offering the potential for India to cut its emissions overall.
Flatlining fossils
Last year, India’s CO2 emissions from fossil fuels and cement grew at their slowest pace in two decades, according to previous analysis for Carbon Brief.
This sharp slowdown was due to rapid clean-energy growth and flat oil demand, combined with rising emissions from steel and cement.
The first half of 2026 marks a continuation of these trends.
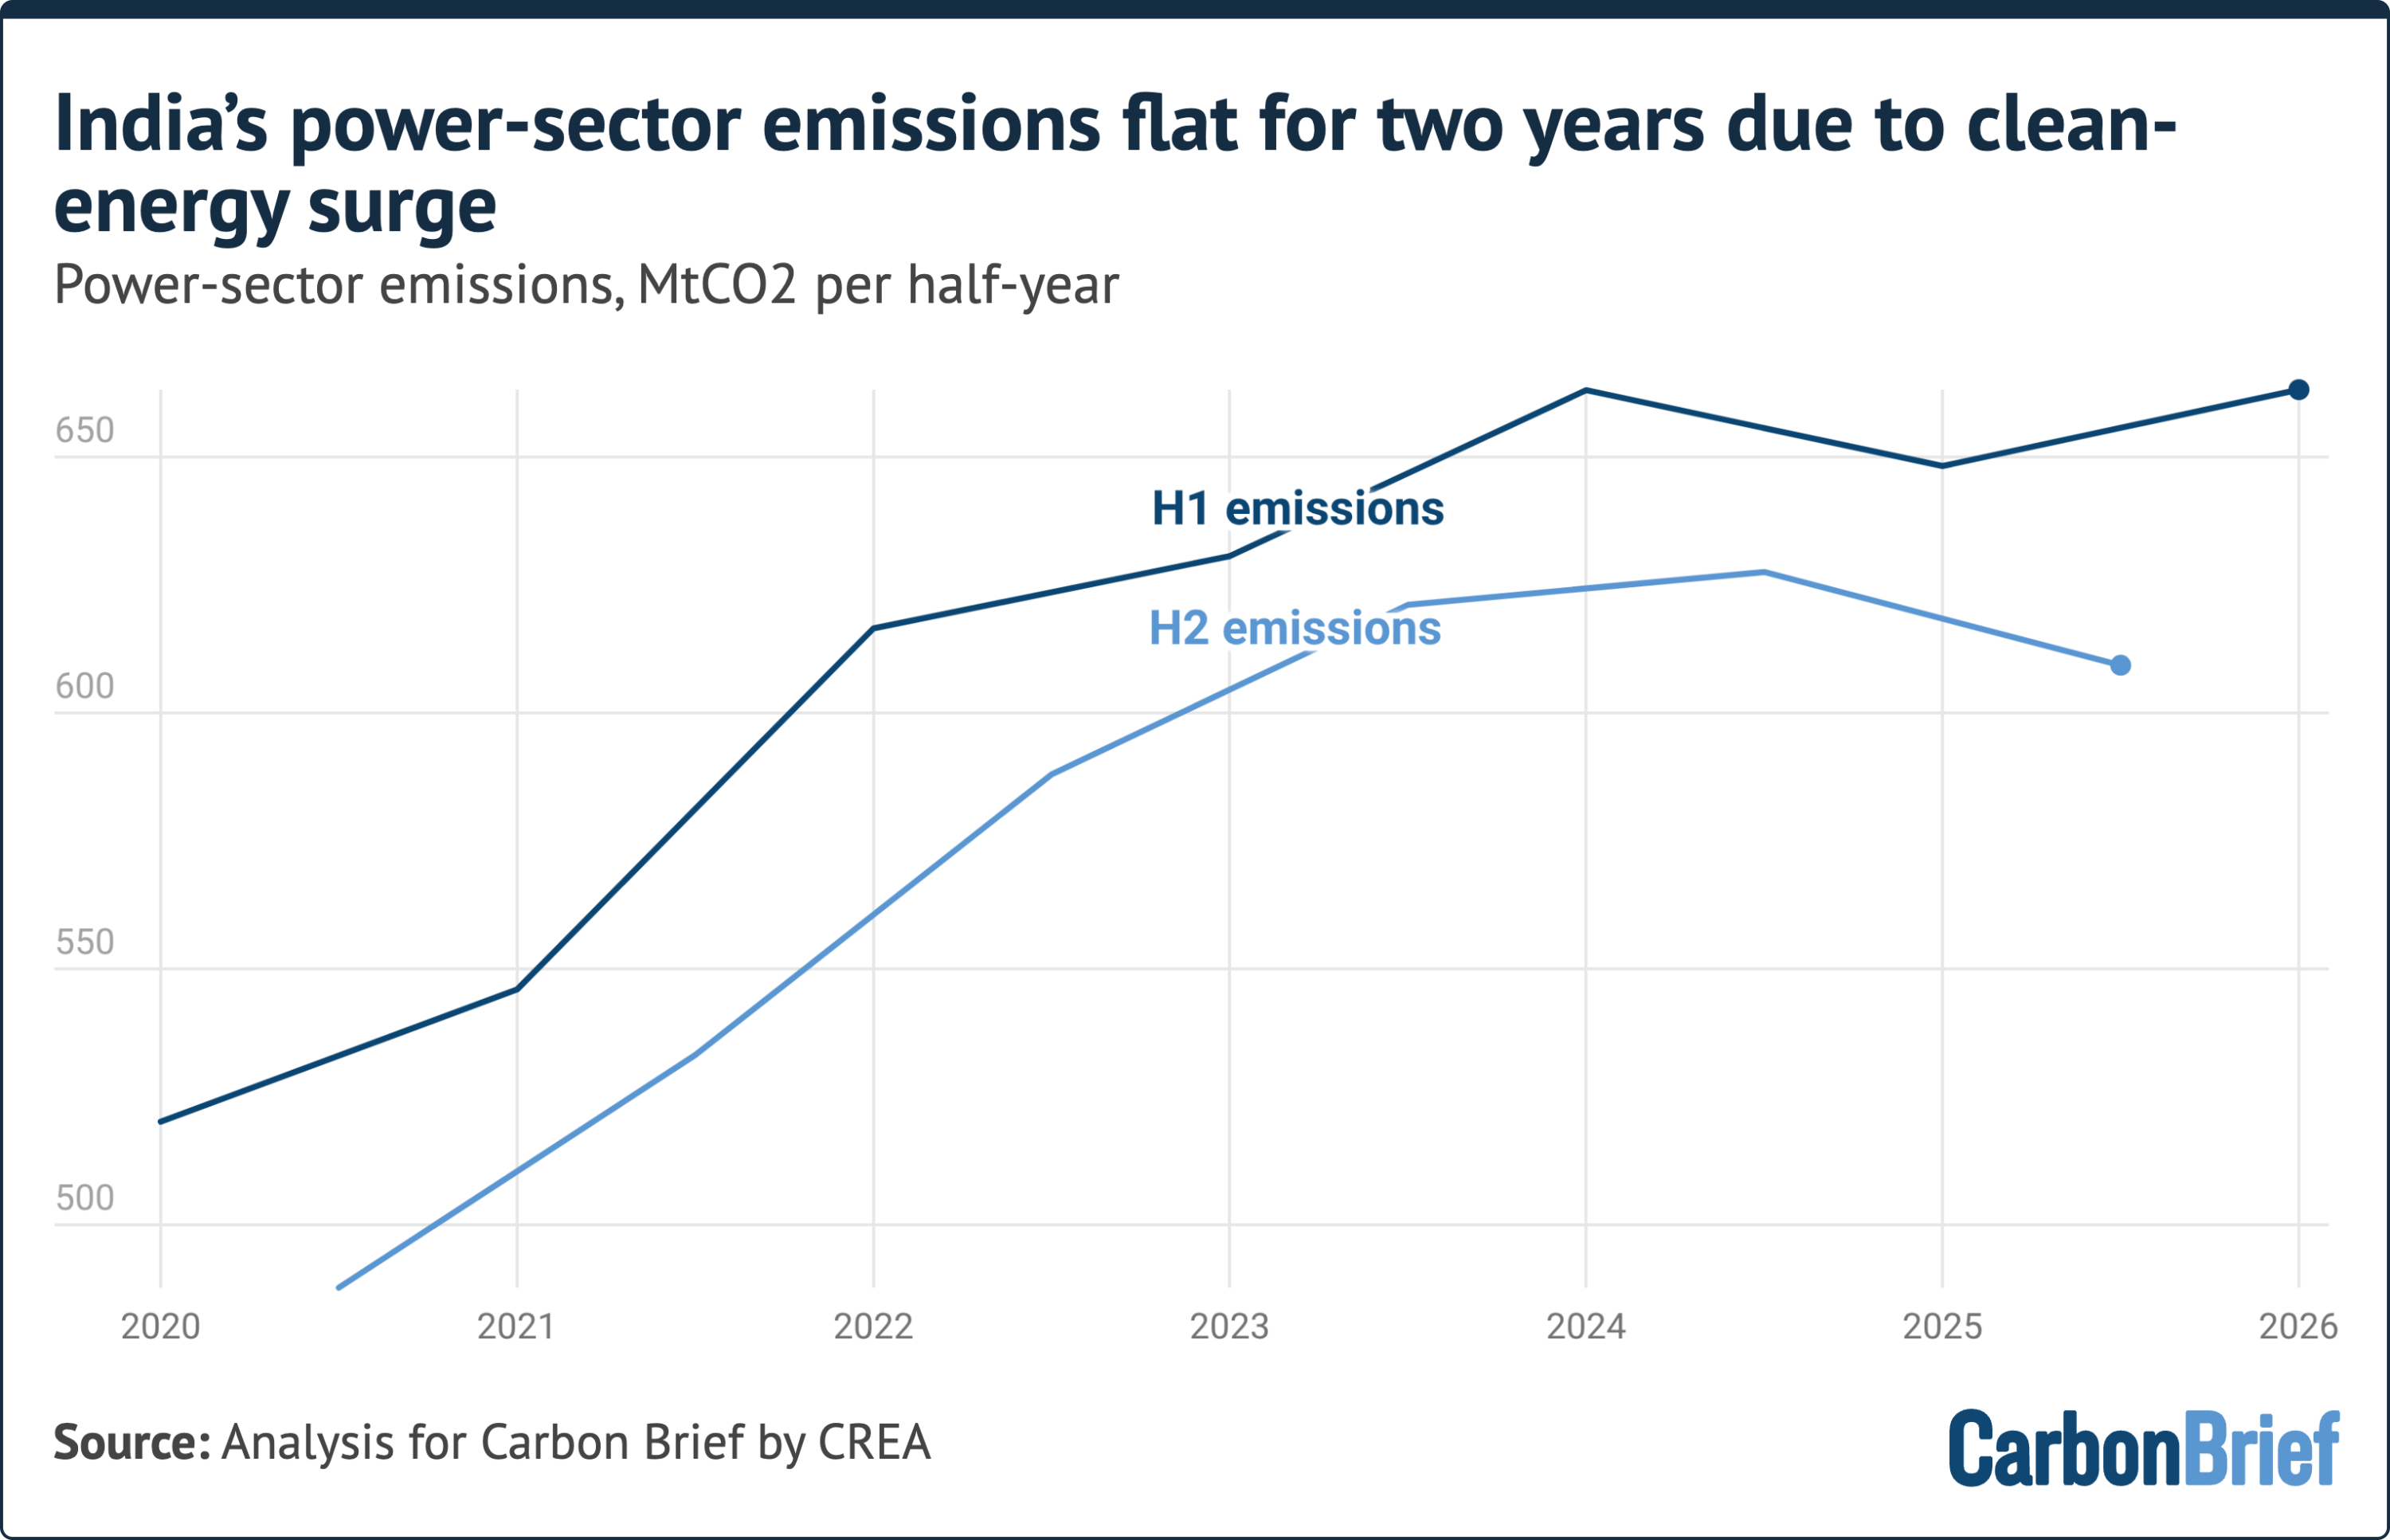
Most strikingly, the ongoing surge in clean-energy generation means that emissions have flatlined in India’s power sector for two years, as shown in the figure below.
Power-sector CO2 was the same in the first half of 2026 as two years earlier, with a small decline in 2025 having been reversed over the same period this year.
Beyond electricity generation, India’s key emitting sectors continued to see divergent trends in the first half of 2026, as some saw ongoing decline while others reached new heights.
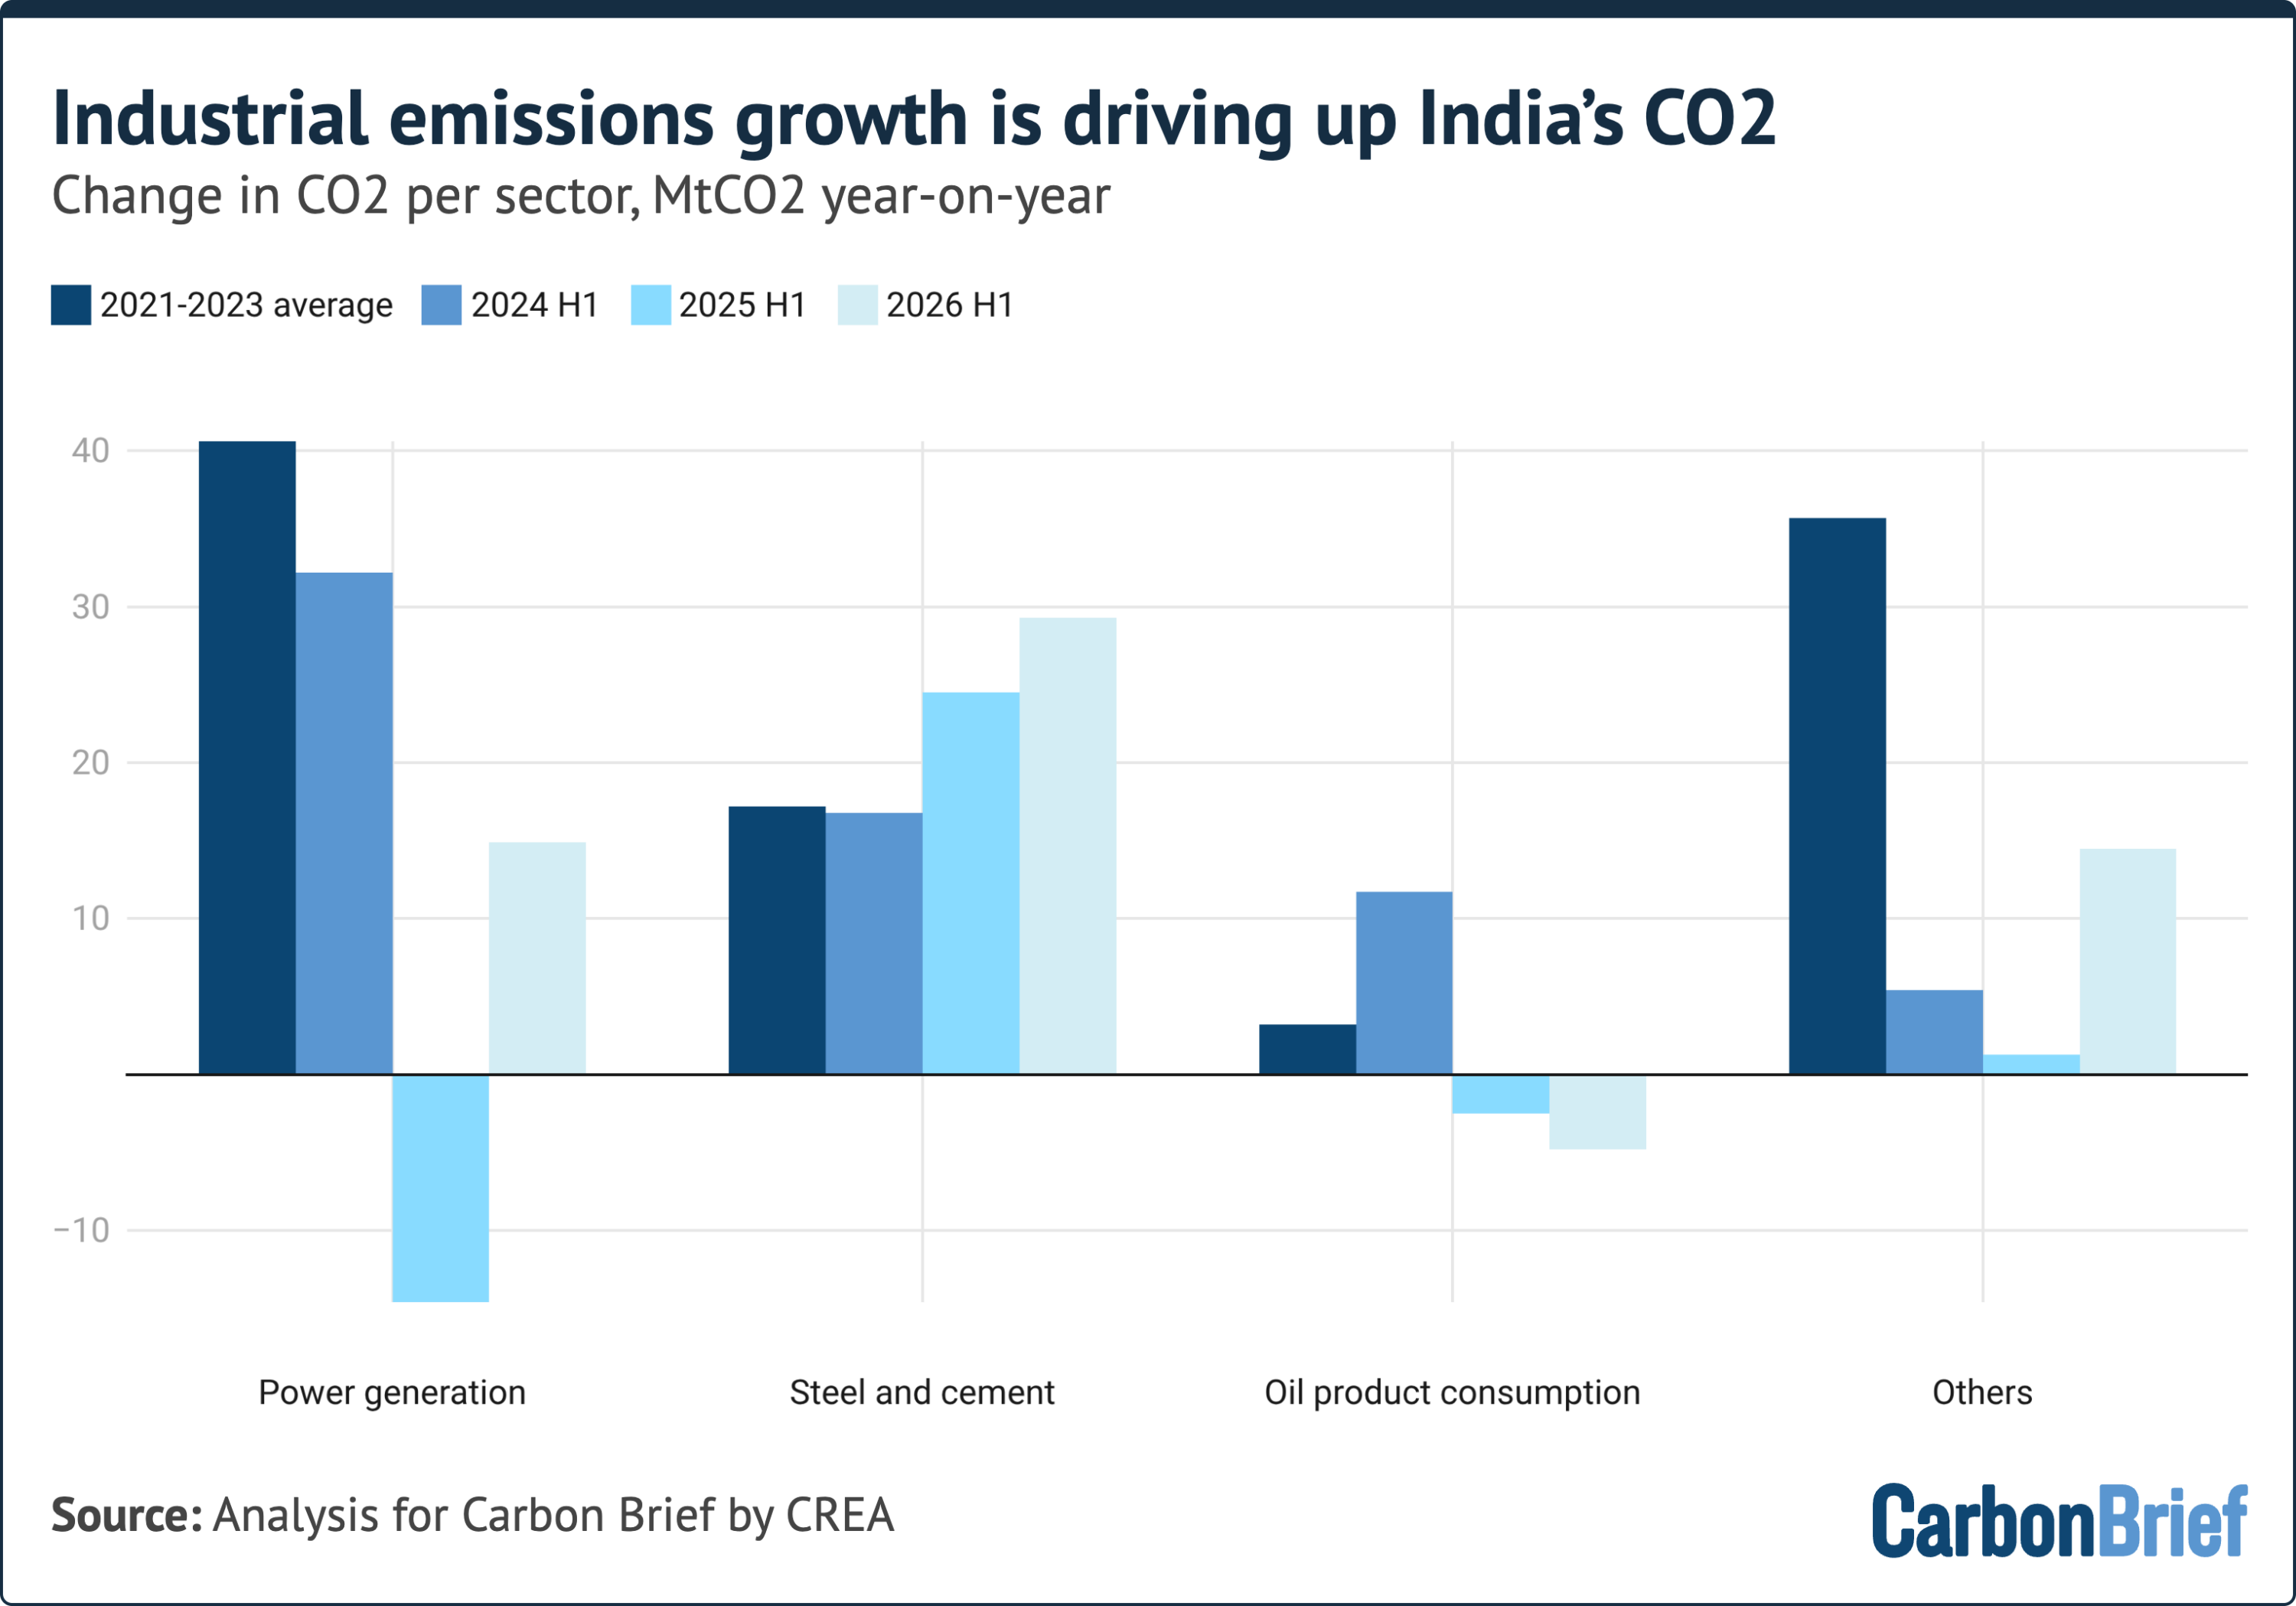
This is shown in the figure below, which compares year-on-year changes in emissions during the first half of 2026 with the same periods in 2025, 2024 and the average for 2021-23.
Specifically, emissions grew by 2.3% in the power sector, reversing last year’s decline, while demand for gas and oil products fell for another year.
The biggest increases were for steel and cement, where emissions growth accelerated to 8% year-on-year in the first half of 2026, well above the recent trend.
Clean-energy growth matches power demand
The period from the first half of 2024 to the first half of 2026 saw the largest increase in non-fossil power generation on record in India.
This enabled fossil-fuel consumption and CO2 emissions from the sector to stay flat, even as electricity consumption increased.
Indeed, this is the first time in more than 50 years that there has been no growth in coal power over a two-year period, even as electricity demand grew overall, as shown below.
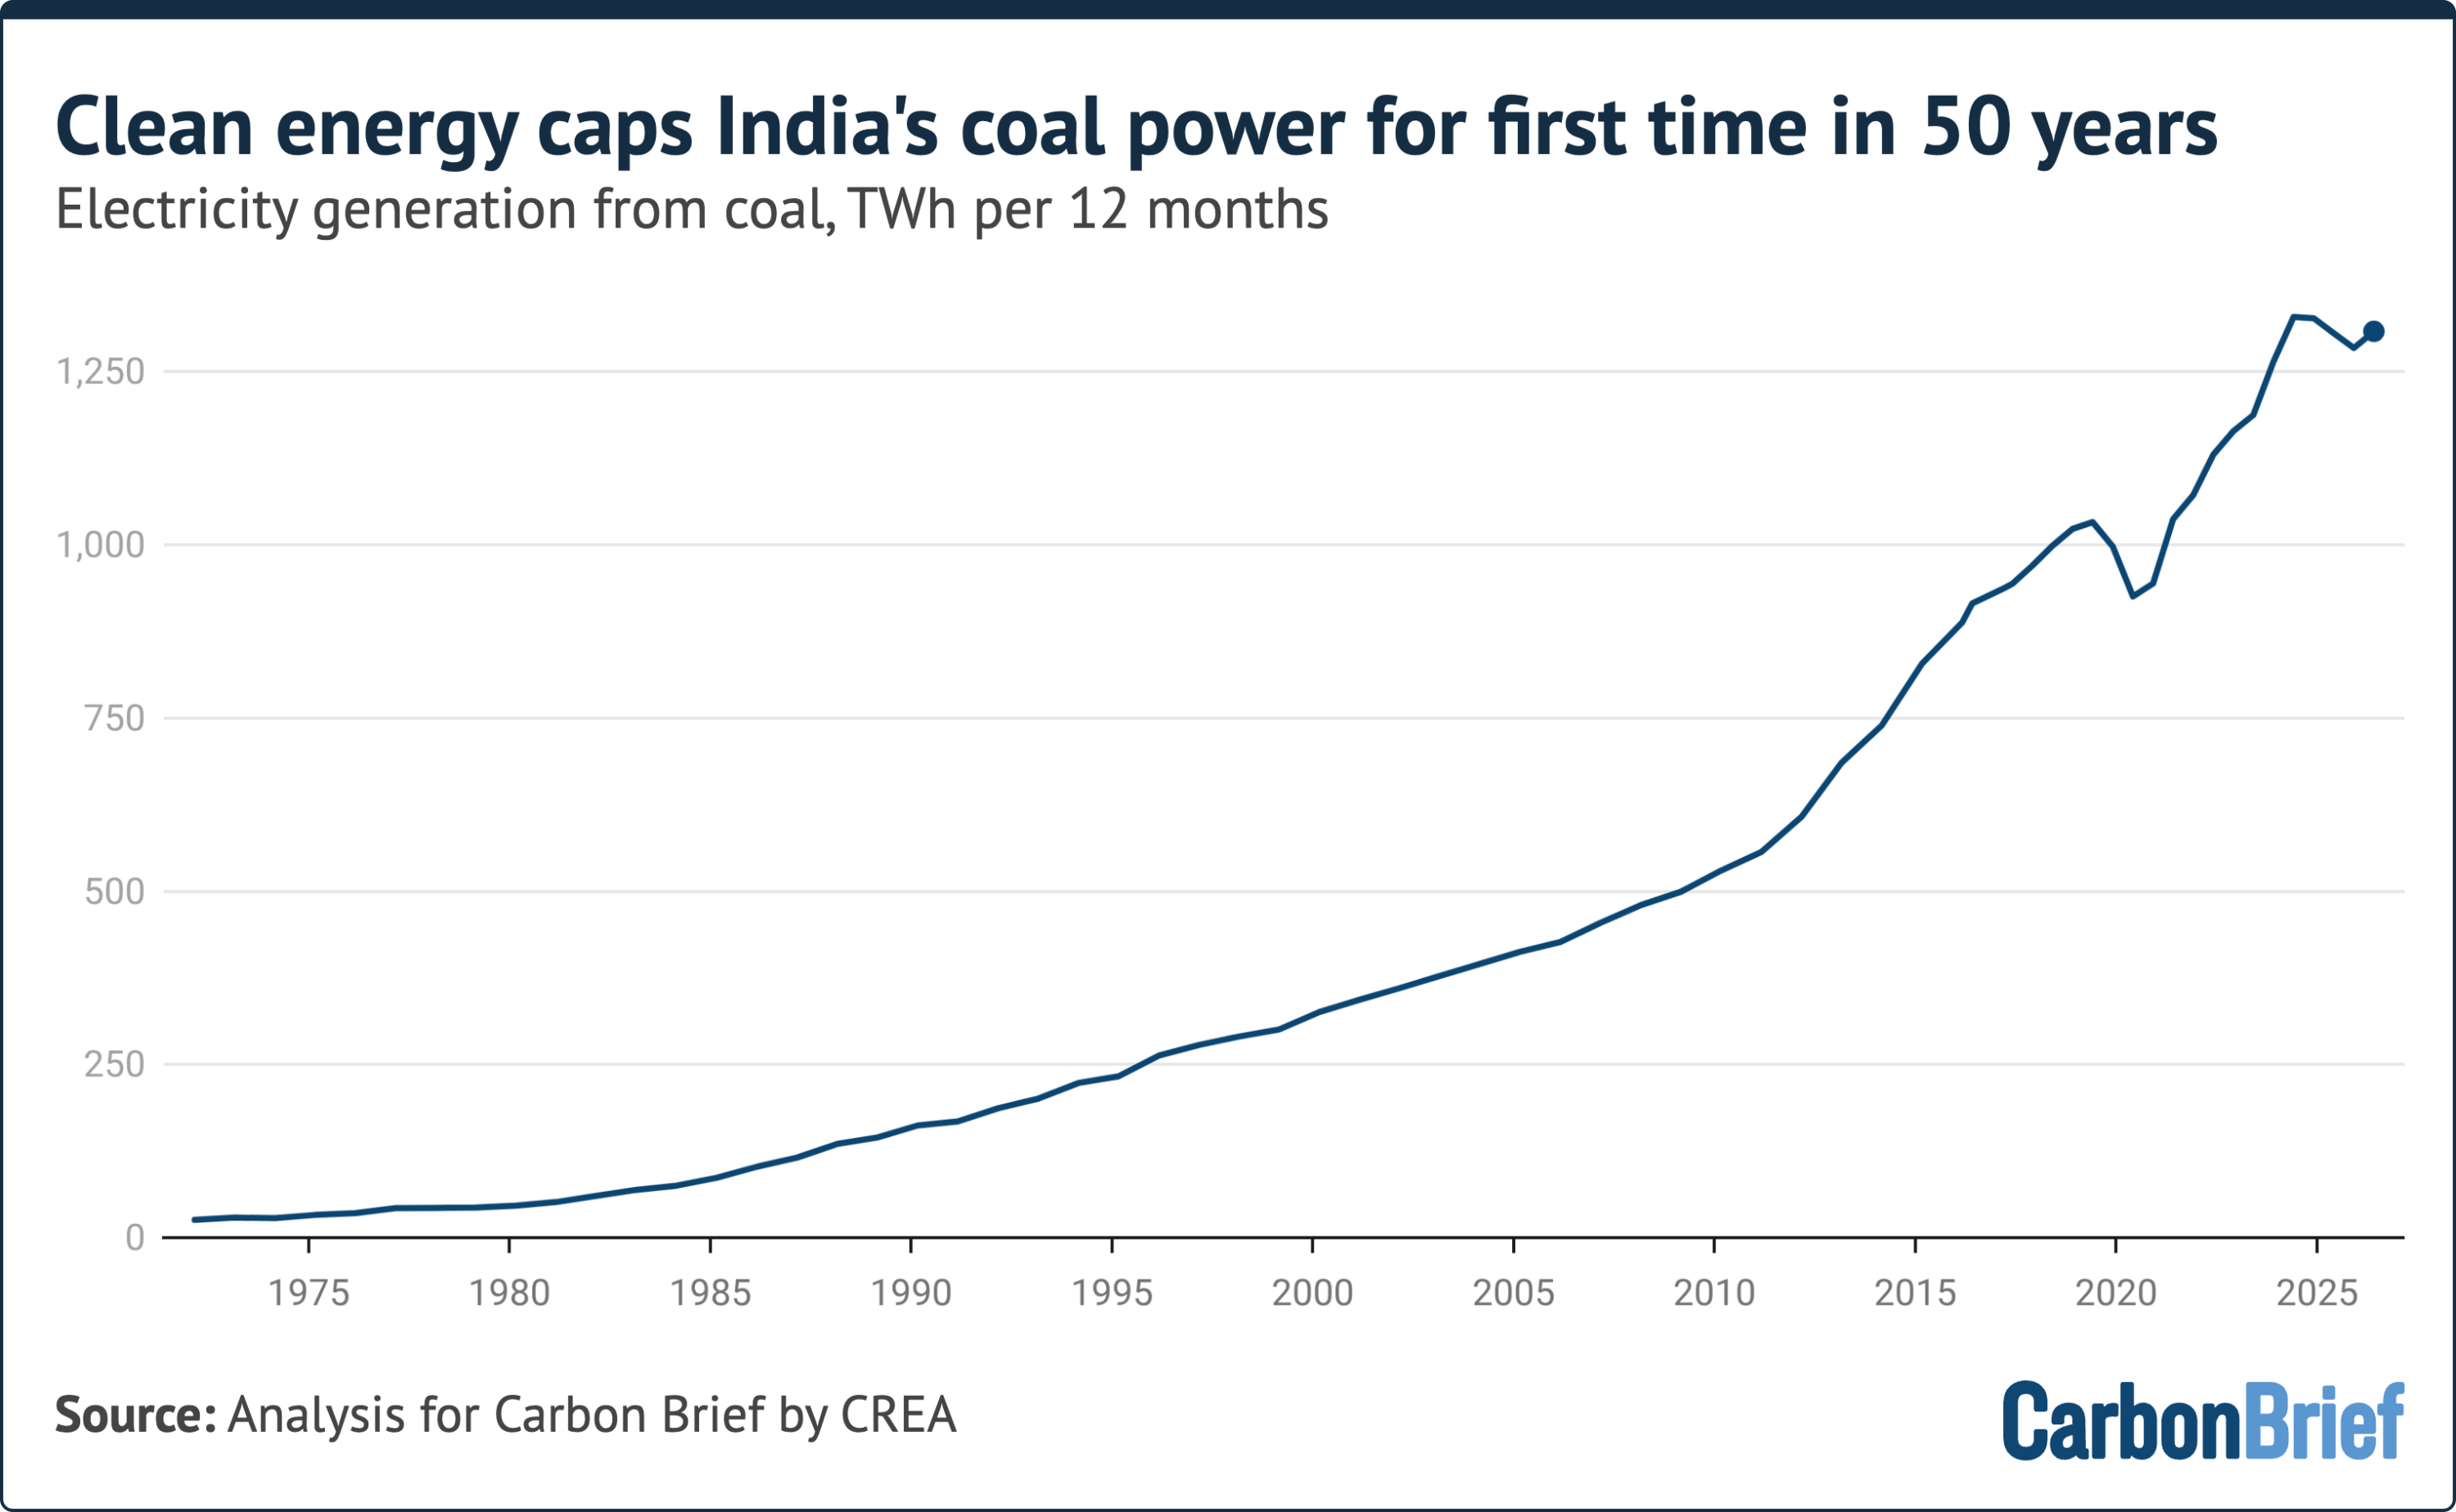
Over this two-year period, India’s total power generation increased by 7%, some 63TWh, equal to the total consumption of Singapore or Switzerland.
The additional power requirement of 63TWh was met entirely by clean energy. Solar grew by 44TWh, alongside growth from wind (13TWh), nuclear (7TWh) and hydro (8TWh).
Together, clean-energy sources added 70TWh over two years, more than the net increase in demand.
(For comparison, China’s nuclear, wind and solar output increased by 485TWh in 2025.)
The figure below shows that new investments are more than sufficient to maintain this trend, as added power generation from new clean power capacity has stayed above average demand growth for the past 18 months.
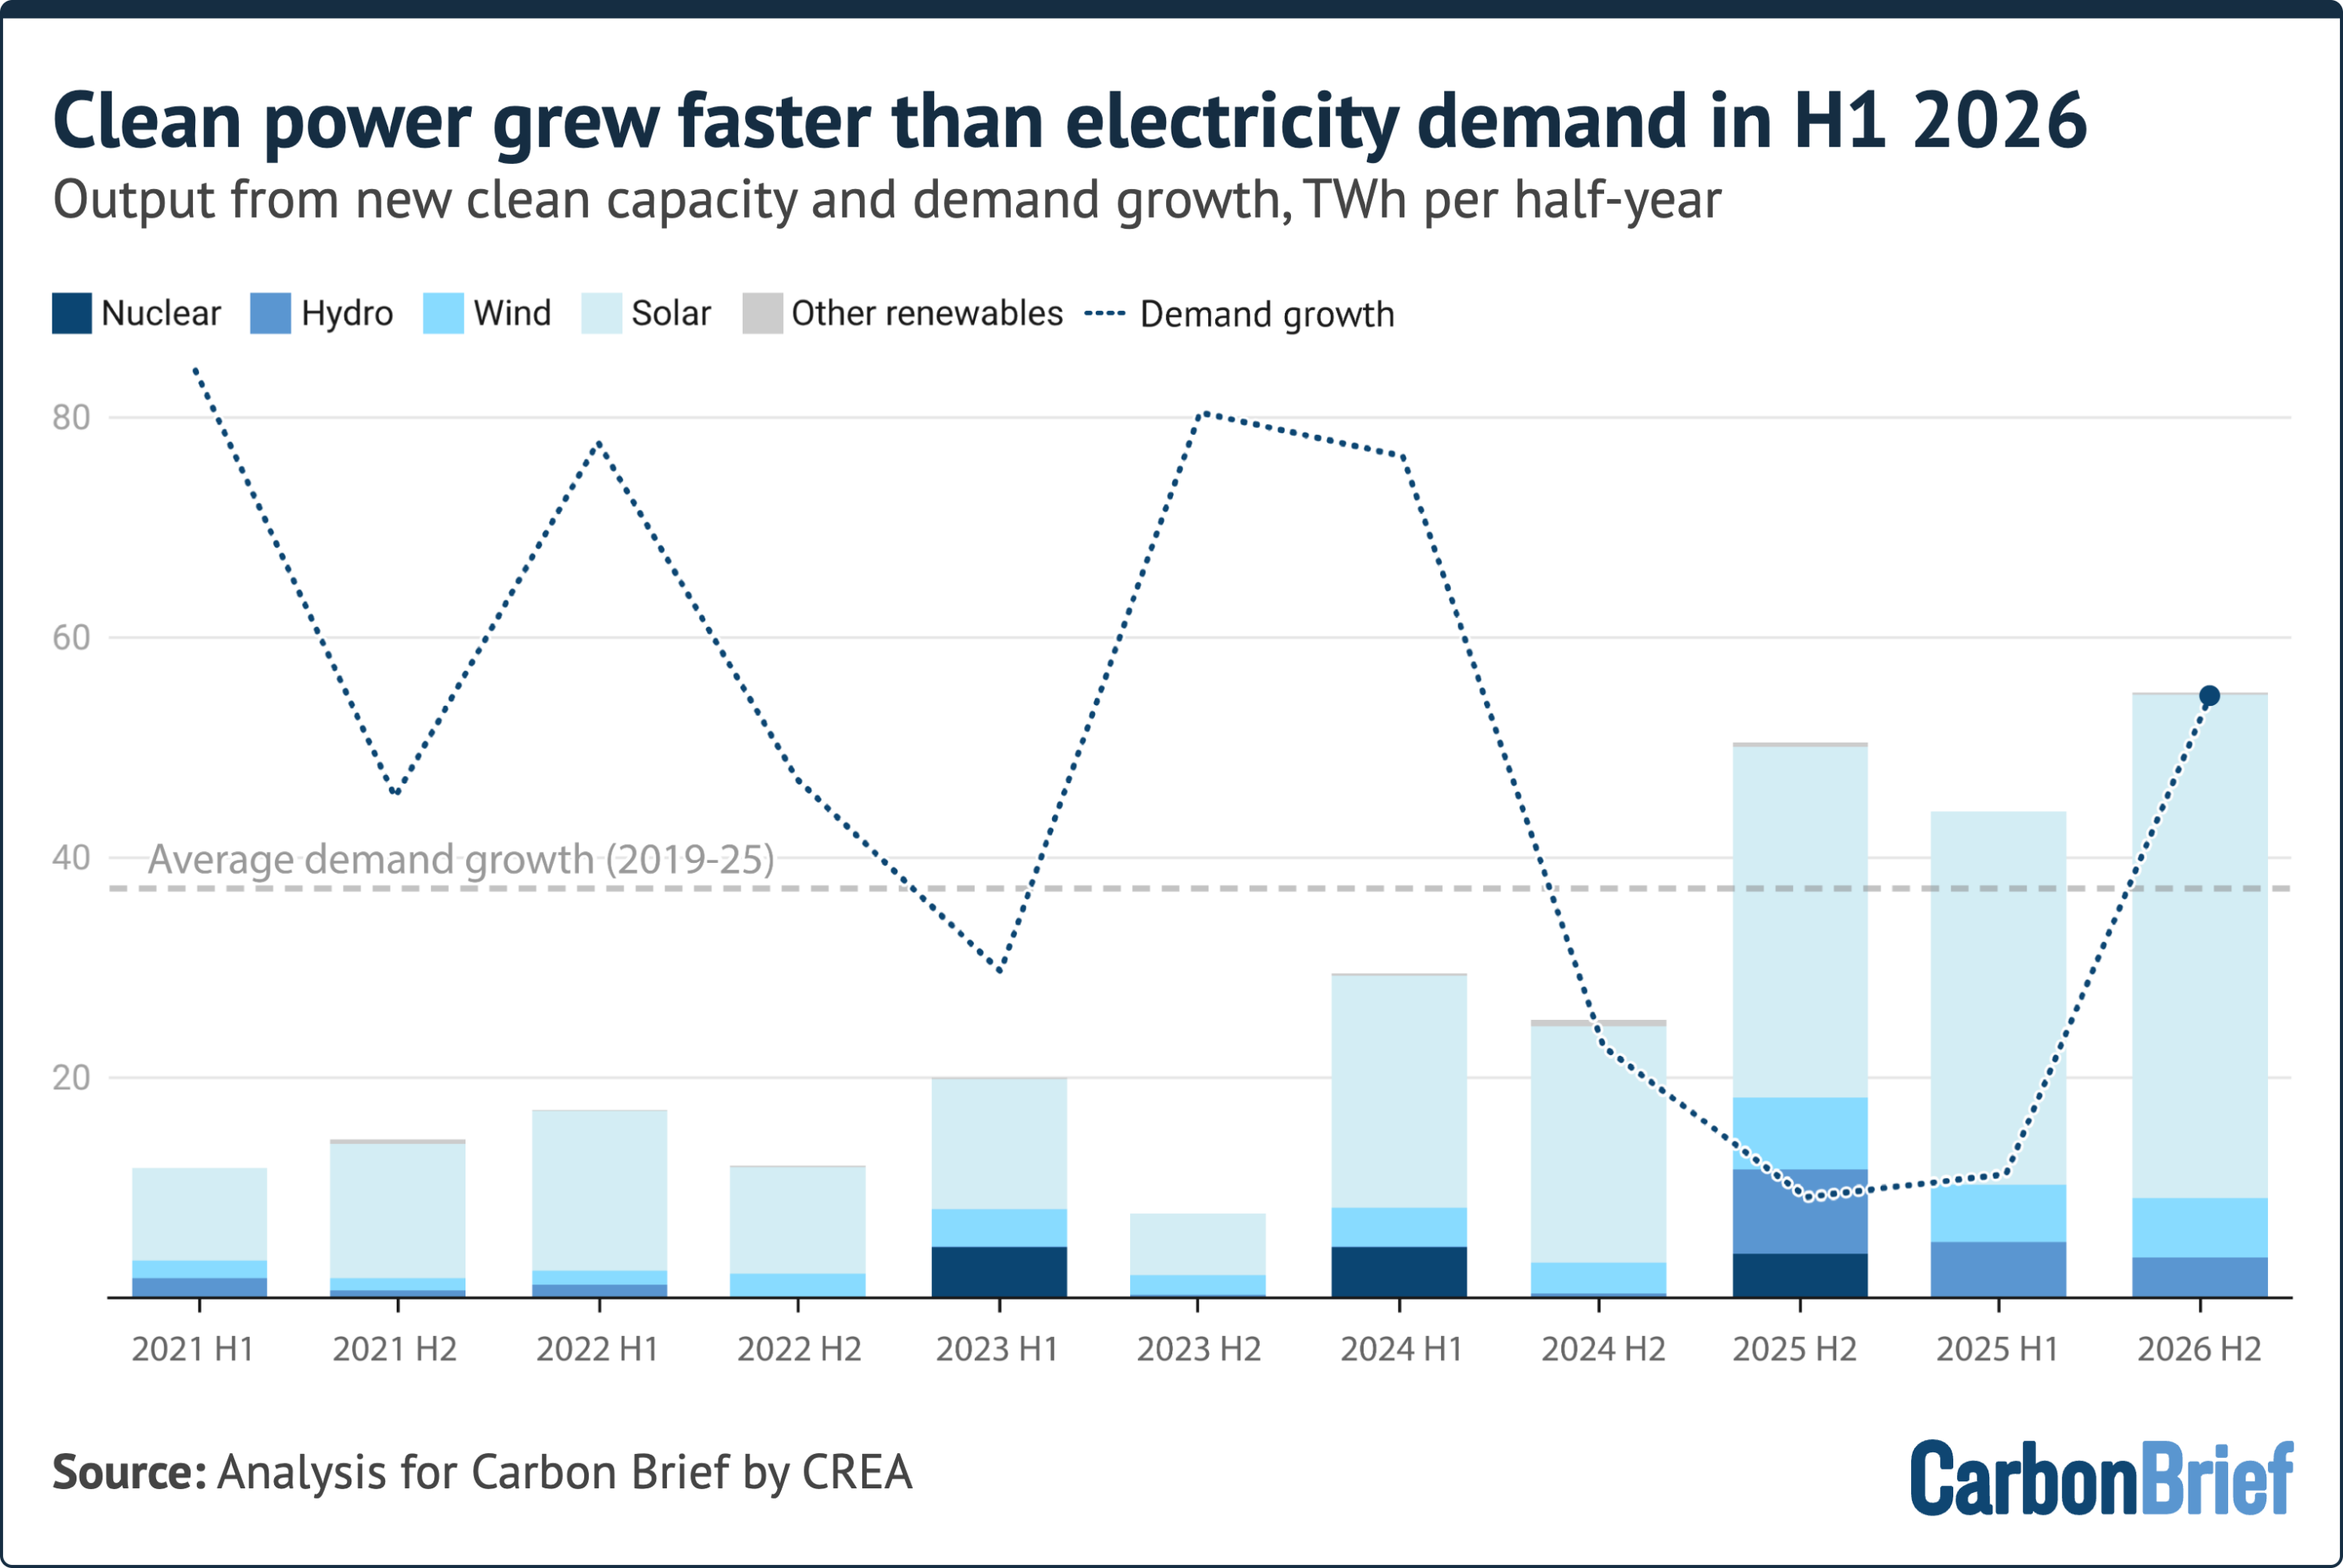
Over the past two years, India added 77GW of new solar capacity, 11GW of wind, 5GW of hydro and 0.6GW of nuclear capacity.
Solar power continues to dominate clean-energy growth, but, collectively, the other non-fossil sources still contributed 40% of the overall increase in generation.
One factor in electricity demand growth in 2026 is the El Niño, which delayed the monsoon and intensified heatwaves, driving up cooling demand.
India is accelerating investment in energy storage, which will support further growth in clean power. The National Electricity Plan projected a requirement of 82 gigawatt-hours (GWh) of energy storage capacity by 2026-27 and 411GWh by 2031-32.
As of May 2026, the government has issued tenders for around 272GWh of energy storage capacity, including 142GWh of pumped hydro and 133GWh of battery storage systems. Current capacity is 7.5GWh of battery storage and around 60GWh of pumped hydro.
Which states led the clean-power shift?
The fall in power generation from fossil fuels from the first half of 2024 to the same period in 2026 was concentrated in a few states.
Gujarat saw both the largest reduction in fossil-fuel generation and the largest expansion in clean power, as shown in the figure below.
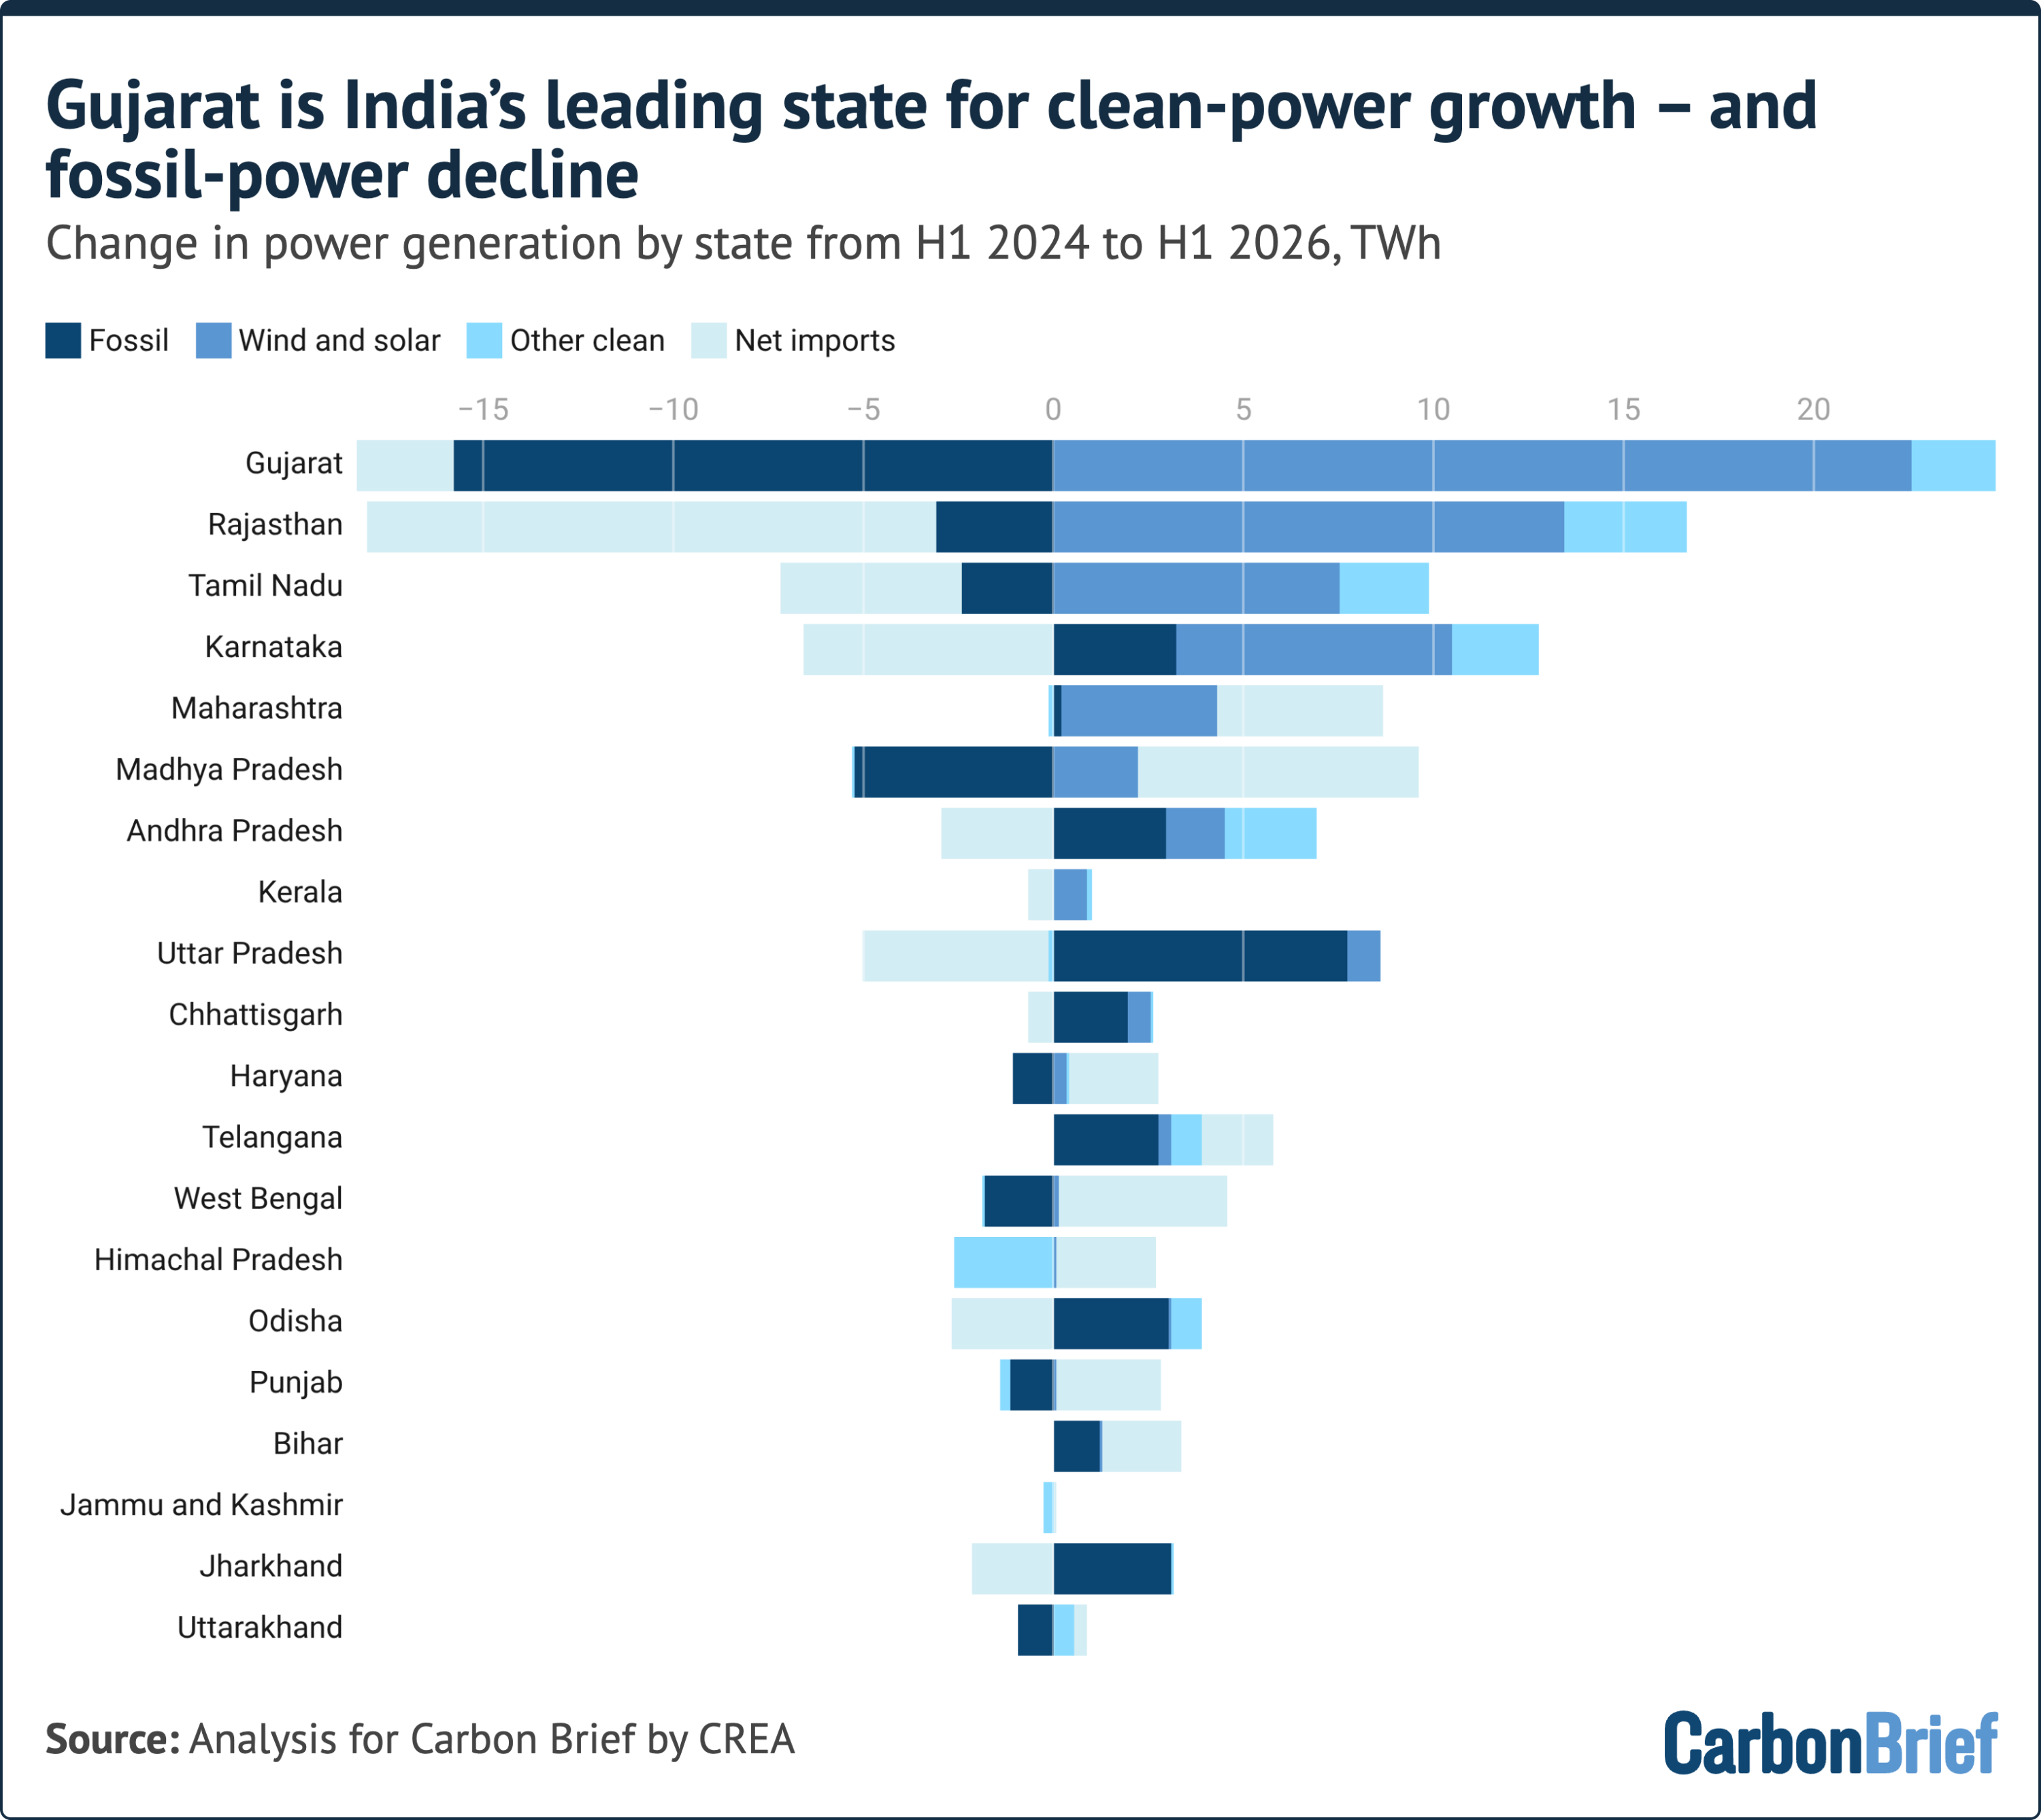
After Gujarat, the largest increases in clean-power generation were seen in Rajasthan and Tamil Nadu, which also saw reductions in power generation from fossil fuels.
Several other states saw declines in fossil-fuel generation due to higher net imports, rather than local clean power. These included Madhya Pradesh, West Bengal and Punjab.
Karnataka and Andhra Pradesh also succeeded in increasing clean-power generation faster than power demand, thereby contributing to keeping fossil fuel-based power generation stable nationwide across the two-year period. However, they exported much of the increase and consequently saw local increases in power generation from fossil fuels.
The two states with the largest increases in power demand, Maharashtra and Telangana, managed to almost match the rise with growth in clean-power generation.
Fall in oil and gas consumption continues
India’s oil consumption continued to fall during the first half of 2026, dropping 1.3% year-on-year, a slight acceleration from the 0.7% reduction in the same period last year.
While diesel and petrol consumption continued to grow, oil consumption was pulled down overall by declines in liquefied petroleum gas (LPG), petcoke (a solid derivative of oil used in the cement industry) and industrial feedstocks. Growth of aviation fuel use eased.
Diesel consumption growth accelerated from 1.8% to 4.1% in the first half of the year, supported by higher freight movement and increased agricultural demand, as the delayed monsoon led to greater use of diesel-powered irrigation.
Petrol consumption returned to growth, increasing 6.9% year-on-year after zero growth in the same period in 2025, reflecting sustained growth in passenger and two-wheeler mobility.
A significant increase in ethanol blending shaved a full percentage point off the growth of petrol consumption. India achieved its 20% ethanol blending target five years ahead of schedule in 2025-26. (Ethanol blending has faced public opposition.)
Electric vehicle (EV) adoption in India is also gaining momentum, with EVs adopted in a widening range of categories.
In Delhi, an EV policy was launched to accelerate electrification of the vehicle fleet, with a particular focus on two-wheelers, three-wheelers (auto rickshaws), commercial vehicles and high-mileage segments, alongside expanded charging infrastructure. Higher EV adoption rates will moderate the growth in emissions from petrol consumption in India.
In contrast, aviation fuel demand growth slowed down from 5% to 2%. The slowdown coincided with the strait of Hormuz and wider crisis, which disrupted international aviation through temporary airspace closures and flight cancellations to several Middle Eastern destinations. Elevated aviation fuel prices also increased airline operating costs, contributing to lower fuel demand.
LPG consumption contracted by 7%, after 5.7% growth in the same period last year, amid disruptions in global LPG markets following the Hormuz crisis.
Petcoke consumption fell 9.9%, more than reversing a 9.3% increase in the same period last year. Rising petcoke prices encouraged cement manufacturers to switch to coal.
Consumption of other petroleum products continued to drop, although the pace of decline moderated from 14% in 2025 to 9% in 2026.
Industrial feedstock use was affected by shortages and price increases.
Naphtha demand contracted as import prices nearly doubled and domestic prices increased by around 60%, prompting petrochemical manufacturers to reduce operating rates and suppress demand for imported naphtha.
Bitumen consumption remained subdued due to slower road construction, driven by persistent land acquisition challenges and higher bitumen costs.
Meanwhile, higher light diesel oil (LDO) prices and shortage of LPG led some industrial consumers to switch back to furnace oil in boilers and heaters, despite the higher air pollutant emissions. Supply of fuel oil to industry increased for the same reason.
Rapid emission growth from heavy industry continues
Steel and cement output in India grew by 8% and 9%, respectively, year-on-year in the first half of 2026, despite rising input prices and weakening profitability.
The growth in steel and cement was supported in part by increased investment in India’s real estate sector, especially in the second quarter. Steel consumption growth outpaced production, implying that inventories built up last year were tapped.
Despite domestic demand growth, profit margins of Indian steel and cement manufacturers remained under pressure for much of the period due to elevated raw material costs – particularly imported coking coal – and higher freight costs stemming from the Hormuz crisis.
The pressure on prices could dampen growth. Cement prices are expected to rise to levels last seen in the 2021-22 financial year, when Russia’s decision to cut back gas exports to Europe drove a sharp increase in fossil-fuel prices.
Outside the steel, cement and power sectors, coal-consumption growth accelerated to 14% in the first half of 2026, up from 3% last year, as the LPG shortage prompted a shift to coal.
Gas shortages resulted in some additional burning of coal for cooking in March and April. The government officially authorised the hospitality industry to use coal, refuse-derived fuel pellets, biomass and kerosene for one month.
The ceramic and tile industry also requested that the government allow the use of coal gasifiers amid the gas shortage. State governments including Delhi NCR, Rajasthan, Tamil Nadu, Gujarat and Maharashtra also allowed industries to temporarily use alternative fuels, including coal.
India’s industrial energy use is dominated by fossil fuels, particularly coal. Indian industry has the second-lowest electrification rate in the G20, as shown in the figure below. The share of electricity in total energy consumption in the sector also lags the world average, in terms of both current levels and the rate of increase.
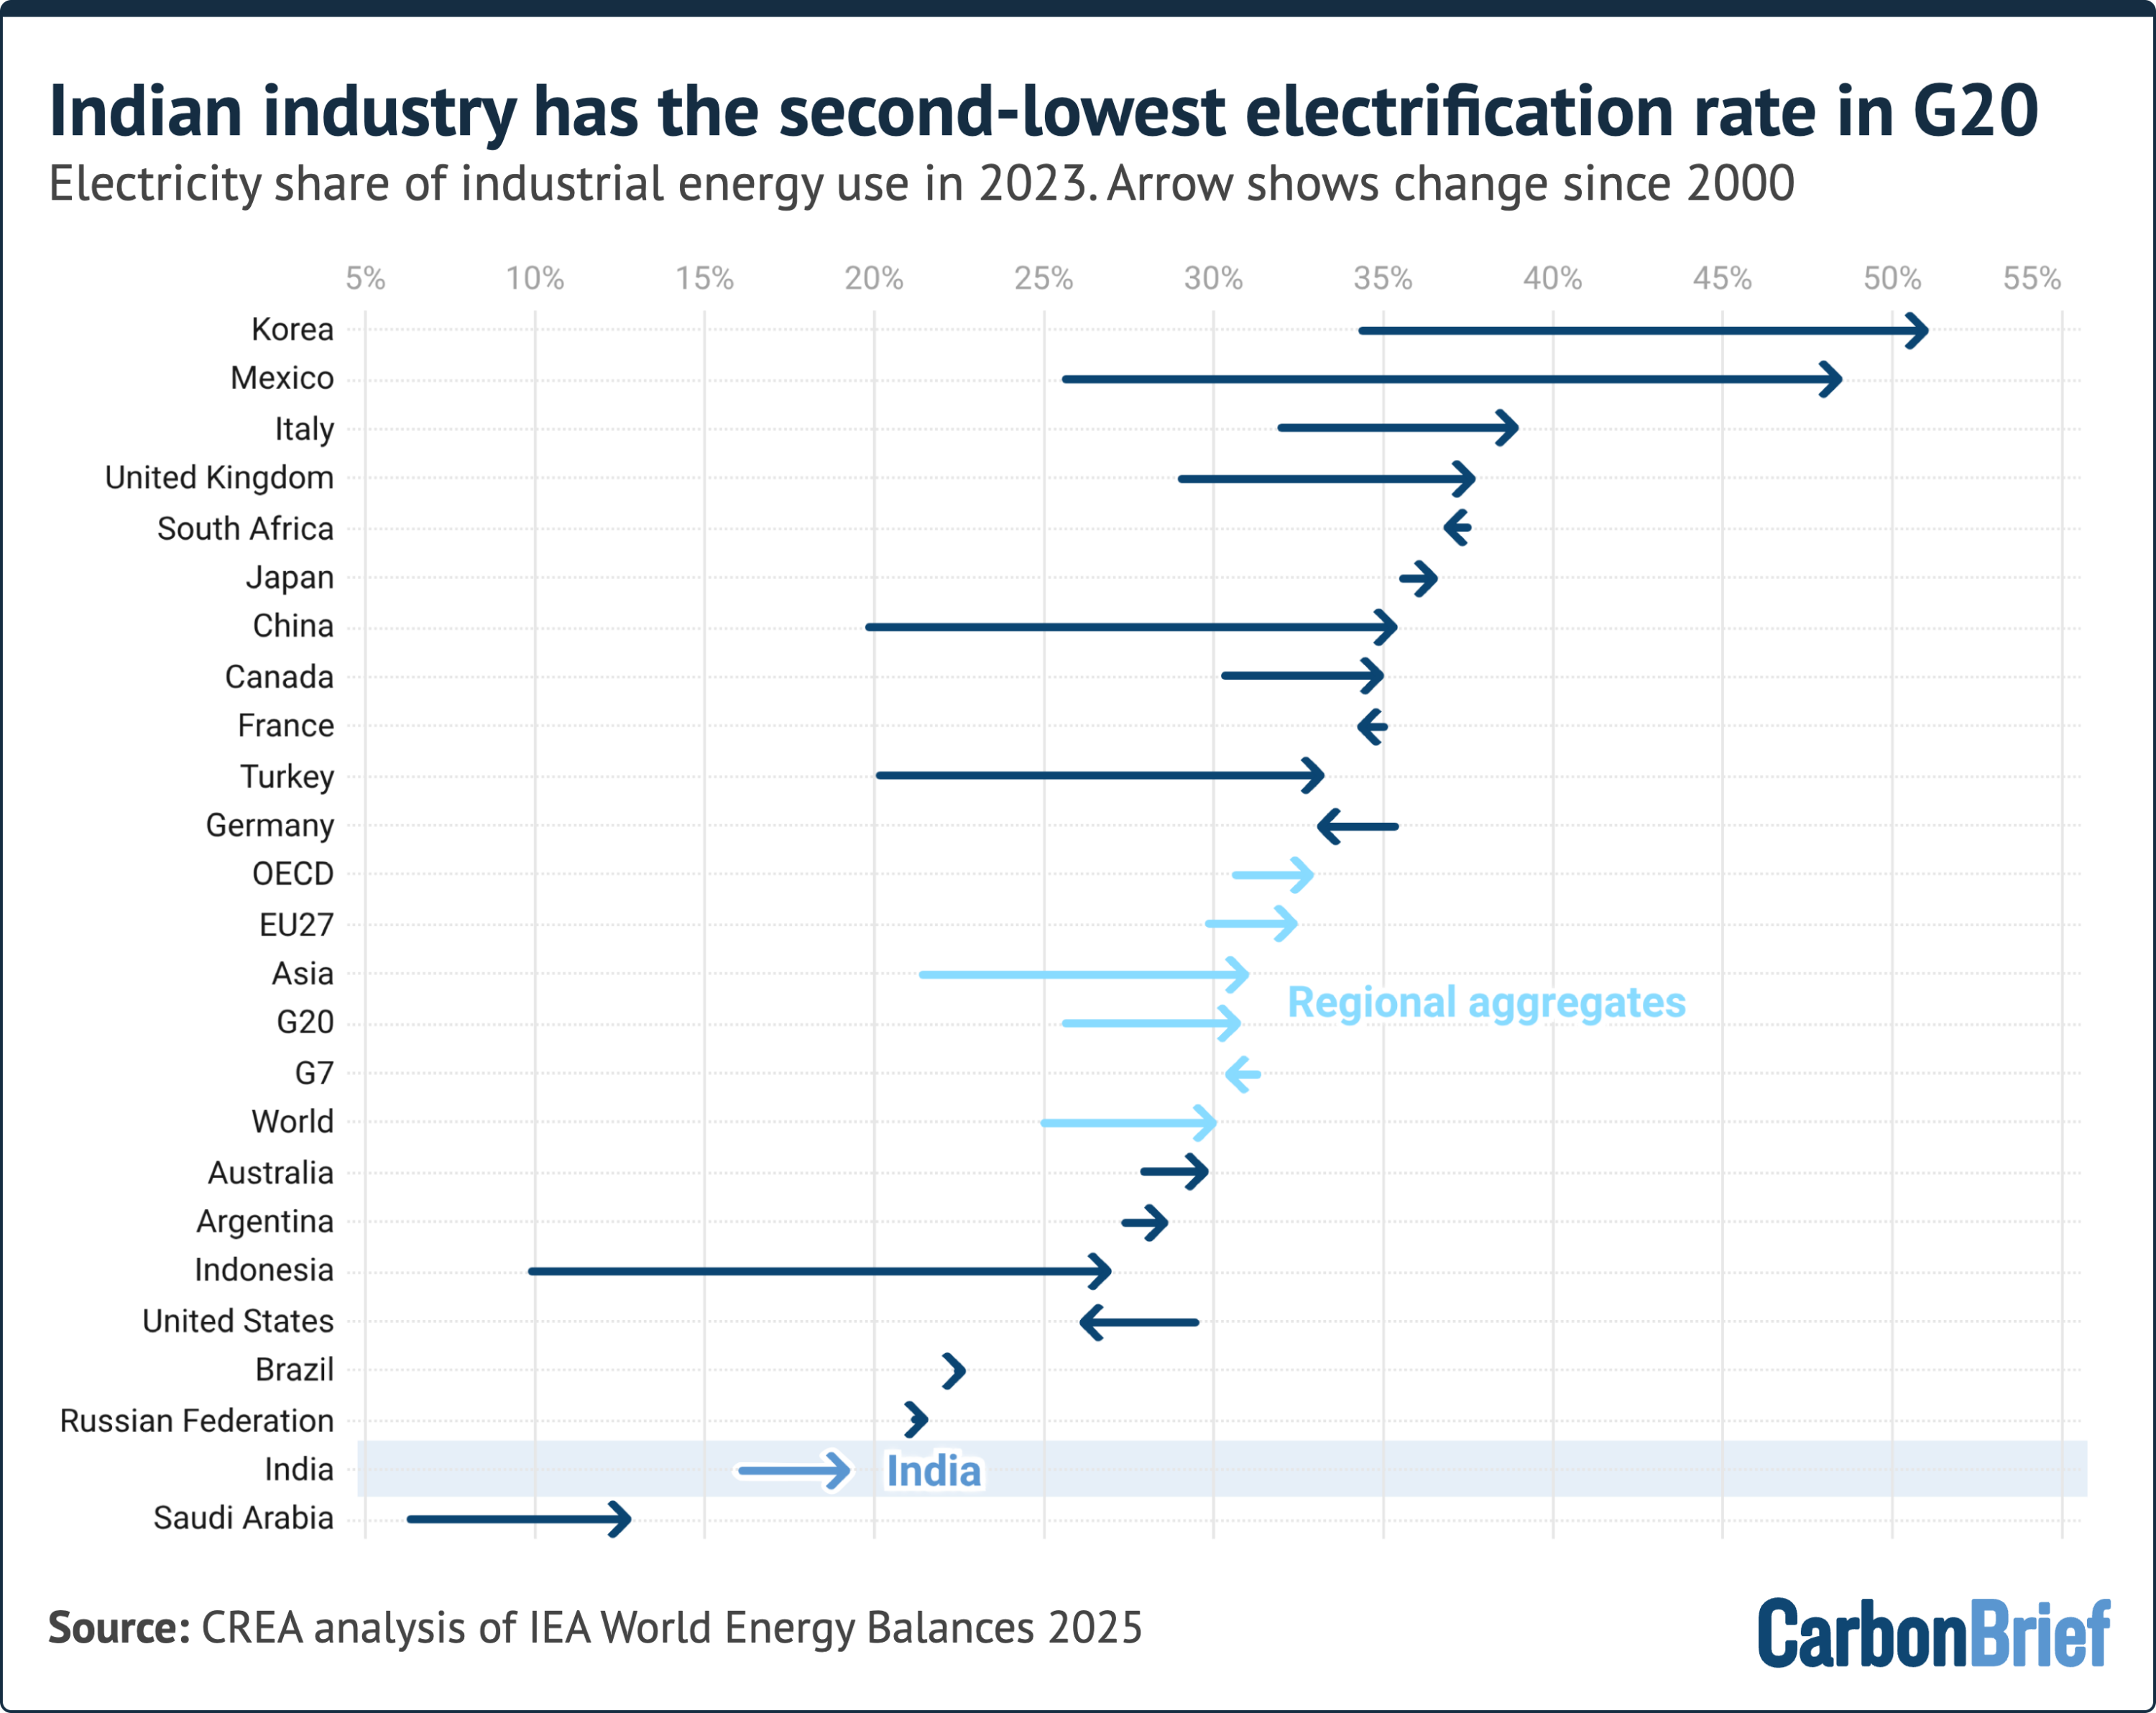
The current low rates of electricity use in Indian industry imply that there is major potential for electrification, using technologies and processes already in place in other countries.
New investments in coal
While the clean-power expansion is starting to meet most or all of India’s electricity demand growth, there are still large investment plans across the coal supply chain.
Some 43GW of coal-power capacity was under construction at the end of June. Additional coal-power capacity is seen as necessary to meet increasing peak loads, even as solar power and energy storage are already playing a role in covering daytime and evening peak demand, respectively. The expansion of energy storage will increase this contribution.
Outside the power sector, India has major ambitions to produce chemical-industry products, such as fertiliser and plastic feedstock, from coal through coal gasification, in pursuit of energy security.
The government is targeting a capacity to process 100m tonnes of coal per year in the next four years, despite the technology for coal gasification still being nascent in India. At present, the only operational use of coal gasification is at Jindal Steel Limited, which is reportedly using syngas in its steel-making process.
Meanwhile, India plans to reduce its average CO2 emissions per tonne of steel by 25% by 2025-26, mainly by reducing the share of coal-based steelmaking.
At the same time, the government is aiming to increase the use of domestic coking coal, which it notified in January this year as a “critical and strategic mineral”. Coal miners and steel companies are reportedly planning to establish additional washeries for coking coal to make it suitable for blending with imported coal for use in steel production.
India is also looking to invest in new coal mines in the near future.
These continued investments in coal gasification, domestic coking coal and new coal mining capacity could lock in coal use across industry for several decades.
Outlook for India’s emissions
Over the two-year period from the first half of 2024 to the same period in 2026, India has achieved its largest clean-energy expansion on record.
As a result, power-demand growth has been met entirely by clean electricity and CO2 emissions in the sector have flatlined.
This expansion of clean energy also allowed a reduction in fossil-fuel imports for power generation, with the use of imported coal falling 38% and the use of gas by 35%, supporting the energy security aims of the government and reducing exposure to the Hormuz shock.
In order to keep the clean-energy growth going, India would need to overcome multiple obstacles, including expansion of the electricity transmission network, improvements in grid flexibility to accommodate variable renewables and the timely completion of new projects.
For example, renewable power projects totalling 5.3GW missed completion deadlines and are having to pay penalties to the grid operator in order to retain network access.
Curtailment has emerged as an issue, particularly for projects relying on interstate power transmission, pointing to the need to upgrade the network. (Curtailment refers to electricity generation that is “wasted” because it cannot be accommodated by the power network.)
Another obstacle to be overcome if clean energy is to keep growing will be making coal-power plants more flexible, so they can ramp down during high renewable output.
A flexibility plan for coal-power plants has been delayed by more than a year due to persistent regulatory bottlenecks, contributing to the curtailment of renewable energy.
Expanding energy storage has the potential to ease grid and flexibility constraints, while reducing or eliminating the need for adding thermal-power capacity to meet peak loads.
The Central Electricity Authority has proposed that, after June 2027, all new government-owned solar and wind projects would have “mandatory” two-hour battery storage. (This mirrors a policy that was in place in China until early 2025 and was subsequently scrapped, in favour of more market-based approaches.)
For oil and gas, India’s consumption has been flatlining for the past two years, after half a century of continuous growth that was only briefly interrupted by Covid-19.
This has reduced the impacts of the Hormuz crisis on the country’s trade balance, helping close the gap between supply and consumption. But it has entailed disruptive shifts in many oil-dependent sectors.
For example, high prices and fuel shortages due to the Hormuz crisis led state governments to reverse their orders banning the use of dirtier fuels such as fuel oil, kerosene and coal in industries and commercial establishments.
Meanwhile, EV adoption has also begun to influence oil consumption.
Despite the progress in the power sector and reductions in oil consumption, India’s total emissions went up over the past two years due to a major increase in industrial emissions.
Low levels of electricity use in industry mean that growing industrial output results in increasing direct fossil-fuel use and emissions.
Unless the rate of industrial electrification picks up, increases in heavy industry output will continue to translate into increases in fossil-fuel consumption and CO2 emissions.
About the data
This analysis is based on official monthly data for fuel consumption, industrial production and power generation from different ministries and government institutes.
Coal-power emissions are estimated by combining plant-level coal consumption from the Central Electricity Authority’s (CEA) monthly coal reports with data on the calorific value and emission factors of coal used at different power plants from the CEA’s CO2 baseline database.
For each station and month, total coal consumption is split into domestic and imported coal using the imported share of coal receipts over a trailing two-month window, found to best reproduce the actual split in data available for 2023.
Consumption is converted to CO2 using each plant’s station-specific gross calorific value from the CEA database and IPCC emission factors for domestic coal, imported coal and lignite. The national-average calorific value is used for recently added plants, for which data is not available in the baseline database.
Coal use at steel and cement plants, as well as process emissions from cement production, are estimated using production indices from the index of eight core industries released monthly by the Office of Economic Adviser, assuming that changes in total fossil-fuel use follow production volumes. These production indices were used to scale fuel use by the sectors in 2022.
To form a basis for using the indices, monthly coal-consumption data for 2022 was constructed for the sectors by combining the annual total coal and petcoke consumption reported in IEA World Energy Balances with monthly production data. This work was set out in a paper by Robbie Andrew, a researcher at Norwegian research institute CICERO, on monthly CO2 emission accounting for India. Monthly petcoke consumption was available from the Petroleum Planning and Analysis Cell, while coal consumption by the cement industry was calculated by subtracting petcoke use from total fossil-fuel use.
Annual cement-process emissions up to 2025 were also taken from Andrew’s work and scaled using the production indices. This approach better approximated changes in energy use and emissions reported in the IEA World Energy Balances, than did the amounts of coal reported to have been dispatched to the sectors, showing that production volumes are the dominant driver of short-term changes in emissions.
For other sectors – including aluminium, auto, chemical and petrochemical, paper and plywood, pharmaceutical, graphite electrode, sugar, textile, mining, traders and others – coal consumption is estimated based on data on despatch of domestic and imported coal to end users from statistical reports and monthly reports by the Ministry of Coal, as consumption data is not available.
Coal consumption by “captive” coal-power plants – those supplying power to industrial sites, not to the public electricity network – was calculated based on capacity changes from Global Energy Monitor, assuming constant utilisation, as utilisation has been very stable year-to-year, as calculated from Central Electricity Authority data.
The difference between coal consumption and dispatch is stock changes, which are estimated by assuming that the changes in the amount of coal stored at end-user facilities mirror those at coal mines, with end-user inventories excluding power, steel and cement assumed to be 70% of those at coal mines, based on comparisons between our data and the IEA World Energy Balances.
Stock changes at mines are estimated as the difference between production at and dispatch from coal mines, as reported by the Ministry of Coal.
Coal consumption is estimated in two ways for sectors beyond power, steel and cement. Consumption of domestic coal in these other sectors is taken from the monthly reports by the Ministry of Coal. Their consumption of imported coal is estimated from the total imports of thermal coal reported by consultancy Kpler, by subtracting demand for imports at coal-power plants. The basis for this assumption is that steel and cement industries use little imported thermal coal, according to Ministry of Coal data.
Product-by-product consumption data for petroleum products, as well as gas use by sector, is from the Petroleum Planning and Analysis Cell of the Ministry of Petroleum and Natural Gas.
As the fuel dispatch and consumption data is reported as physical volumes – such as tonnes or litres – calorific values are taken from IEA’s World Energy Balance and CO2 emission factors from 2006 IPCC Guidelines for National Greenhouse Gas Inventories.
The emissions factor for motor oil or petrol was updated, based on the blending percentage of ethanol each year. The ethanol-blending percentage is as reported by the Ministry of Petroleum and Natural Gas.
Calorific values are assigned separately to different fuel types, including domestic and imported coal, anthracite and coke, as well as to petrol, diesel and several other oil products.
related
Explainer: The CMIP7 emissions scenarios – and how they explore future climate change
UNEP: New country climate plans ‘barely move needle’ on expected warming
Analysis: India’s power-sector CO2 falls for only second time in half a century